Serving St. Charles and St. Louis families
Jones Elder Law lighthouse logo
Jones Elder Law
Protecting your home, savings and spouse
Talk with an attorney636.493.3333

Already in a Missouri nursing home

Loved one in a Missouri nursing home? Call a Medicaid planning attorney before you pay another bill.

Every month of private pay can drain savings your family may be able to keep. Nursing home admission does not end your options, but the order of your next steps matters, and some mistakes cannot be undone. An elder law attorney can tell you what to do first, and what to stop doing today.

The short answer

Is it too late? No. Many lawful Medicaid planning steps can still be taken after admission. What can be protected depends on whether the person is married or single, the assets involved, past transfers, and timing.

The first call is complimentary. Rosalind M. Robertson, an elder law attorney, takes it herself, and our goal is to return every request within one business day. If we recommend a plan, we explain the work and the fixed fee before you decide.

20+ yearsfocused on elder law and Medicaid planning
1,000+planning, implementation, and application experience
Attorney ledfrom the first conversation through determination
★★★★★ 5.0 on Googlefrom 49 client reviews
Rated Superb on AvvoStephen C. Jones, 9.9 · Rosalind M. Robertson, 9.5
Endorsed by fellow elder law attorneysPeer endorsements on both attorneys’ Avvo profiles

One call changes the next step

Here is what changes after one phone call.

You are already carrying a lot. You should not have to work out Medicaid rules on your own while the bills keep coming.

Your savings

Know what may still be protected.

Before another bill is paid, we review the home, the savings, and the income, so you know what Missouri’s rules may allow your family to keep.

Your time

Stop guessing and get an order of steps.

We tell you what to do first, then prepare the plan and file the Medicaid application to match it, so nothing works against something else.

Your peace of mind

Put down the fear and the paperwork.

One conversation with an attorney replaces searching late at night. You will know where you stand, what comes next, and who is handling it.

Call 636.493.3333

The first call is complimentary. Rosalind M. Robertson takes it herself.

“We had been told that Mom had to spend down almost everything before she could qualify for Medicaid. Jones Elder Law explained that we still had options and showed us how a substantial portion of her savings could be protected. I am so grateful that we called before filing the application or spending the money.”

Delores · Jones Elder Law client

The cost of waiting

Every month of private pay is money that is not coming back.

Nursing home bills add up fast. Each month a family waits, savings that a plan might have protected can go to the facility instead.

Six months can be a large share of what a family has saved. The sooner an attorney reviews your situation, the more options you may still have.

Based on the general experience of our clients: about $10,000 per month for private pay nursing home care.

Why we do this work

We have lived what your family is living through.

My grandmother lived with Alzheimer’s for more than 15 years, and for nine and a half of them she was in a nursing home. Her body was healthy, but she no longer knew where she was or who was in the room. My grandfather grew up with almost nothing and built a comfortable retirement from a couple of gas stations he owned. I watched him spend nearly all of it on her care.

I saw what it does to a person, and what it does to a family.

I also watched my father work through the hard parts of caring for aging parents, including whether they were ready to give up control and let someone else help make decisions. Years later, when my father developed a brain tumor and was left largely paralyzed at age 69, we went through it all again. That time we were prepared, and we were grateful for it.

Rosalind has her own version of this story. Both of her grandmothers spent time in nursing homes, one with Alzheimer’s and the other after a fall. As a young adult she spent many Fridays visiting her grandmother, alongside her mother, who was there so often that she ended up helping in the activities department.

Because of this, we understand how a long-term care crisis can go wrong, and we understand how it can go right. We treat every family the way we would want ours to be treated.

Stephen C. Jones and Rosalind M. Robertson
What to do now

Do not make a decision that cannot be undone. Gather the facts first.

Many families believe they have two choices: keep paying privately, or give everything away. Neither is true. The goal right now is to keep every lawful option open while the full picture is reviewed.

01

Do not make gifts

A gift to a child can create a penalty period under Medicaid’s five-year lookback, and it can cause tax problems. Even a gift made with good intentions can delay coverage.

02

Watch the filing date

Timing can affect which month Medicaid pays from. Waiting too long, or missing a request from the state, can also cost coverage. The plan and the application must work together.

03

Do not sell blindly

Cashing out a retirement account, selling real estate, or surrendering an annuity can trigger taxes and penalties, or close off a planning option.

04

Collect the facts

List accounts, property, income, insurance, annuities, past gifts, estate documents, and who holds legal authority to act for your loved one.

The order matters

A calm path from the first call to a filed application.

Families come to us in the middle of a crisis. Here is how the work is organized, so you always know what happens next and who is doing it.

1

Call an attorney

Rosalind M. Robertson takes the first call and learns what is happening.

2

Hold every payment

You pause gifts, sales, and withdrawals until the facts are reviewed.

3

Vision Meeting

Stephen C. Jones reviews the full picture and explains the options.

4

Plan and carry out

We explain the work and the fixed fee first, then carry the plan out with you.

5

File and follow through

The application is filed to match the plan, and we follow it to a decision.

Two different paths

Married and single applicants are not treated the same.

Missouri gives a spouse who stays at home important protections. A single or widowed person may still have options, but the plan and its timing are very different.

When one spouse needs care

Protecting the healthy spouse

The state’s initial Division of Assets is a starting point, not always the final answer. A coordinated plan may protect the home and turn extra savings into income for the spouse at home.

  • ✓Review who owns every asset
  • ✓Calculate the spouse’s protected share
  • ✓Protect the home and exempt property
  • ✓Time each step with the filing date
Learn about protecting the healthy spouse

When the person is single or widowed

Preserving part of the savings

A single person cannot use the spousal protections. Depending on the facts, a careful plan may keep part of the estate by paying privately for a planned length of time, then moving to Medicaid at the right time.

  • ✓Review the home, farm, and investments
  • ✓Check gifts made in the five-year lookback
  • ✓Compare trust, note, and annuity options
  • ✓Plan for taxes and where payments come from
Learn about individual asset protection

A general illustration

Care has already started. The planning window has not closed.

Picture a parent admitted to a Missouri nursing home last month. The family has been paying the bill from savings while they decide what to do. No Medicaid application has been filed yet.

Admission does not erase the options. It changes the order in which things must happen, and the clock now runs on the facility’s timeline. The home, the savings, and any past gifts still need review before anything else is paid or sold.

Have the admission date, the monthly charge, and recent statements ready, and have the situation reviewed before the next payment goes out.

What families say

In their own words.

“Jones Elder Law has served our family since my wife’s mother suffered a stroke and entered dementia care. They guided us through every change we needed to make.”

Robert, Jones Elder Law client

“When Dad could no longer remain at home, I was trying to find a nursing home, manage his finances, and understand Medicaid all at once. Jones Elder Law gave us a clear plan and handled the legal and Medicaid work that I did not know how to manage. They took an overwhelming situation and made it manageable.”

Susan, Jones Elder Law client

“The Medicaid application required far more information and documentation than we expected. Jones Elder Law told us what was needed, organized the process, responded to questions from the agency, and stayed involved until the matter was completed. Having an experienced firm handle it removed an enormous burden from our family.”

Staci, Jones Elder Law client

Testimonials reflect the experiences of individual clients. Every matter is different, and past results do not guarantee a particular outcome.

Your attorneys

The names on the door are the attorneys working with your family.

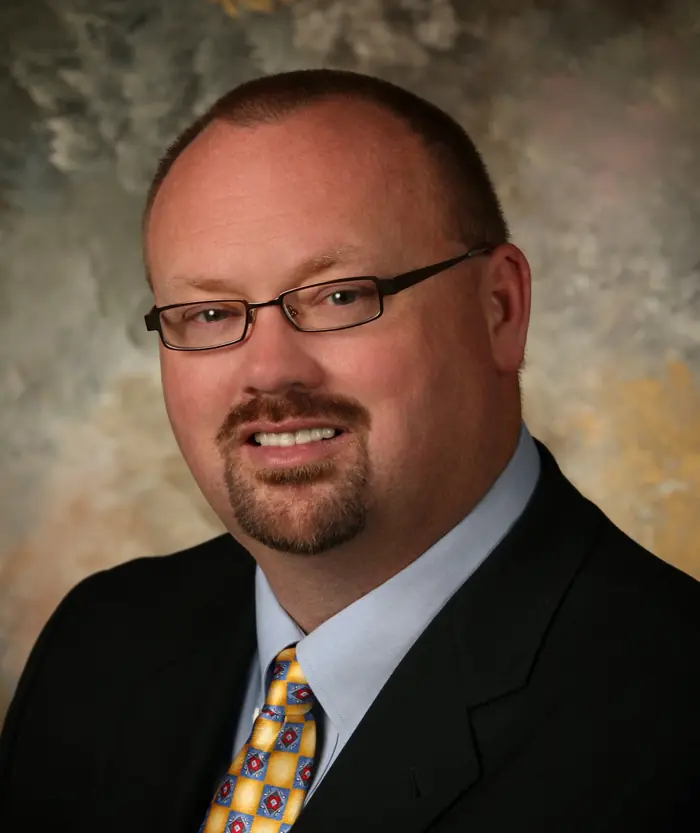
Portrait of attorney Stephen C. Jones

Stephen C. Jones

Founder

Stephen watched his grandmother live with Alzheimer’s for more than 15 years, nine and a half of them in a nursing home. He watched his grandfather, who had built a comfortable retirement from his own gas stations, spend nearly all of it on her care. Years later, his father’s brain tumor put the family through the process again, and this time they were prepared. Before founding Jones Elder Law, Stephen handled high net worth estate planning at a large St. Louis law firm. Admitted in Missouri (1999) and Illinois (2006).

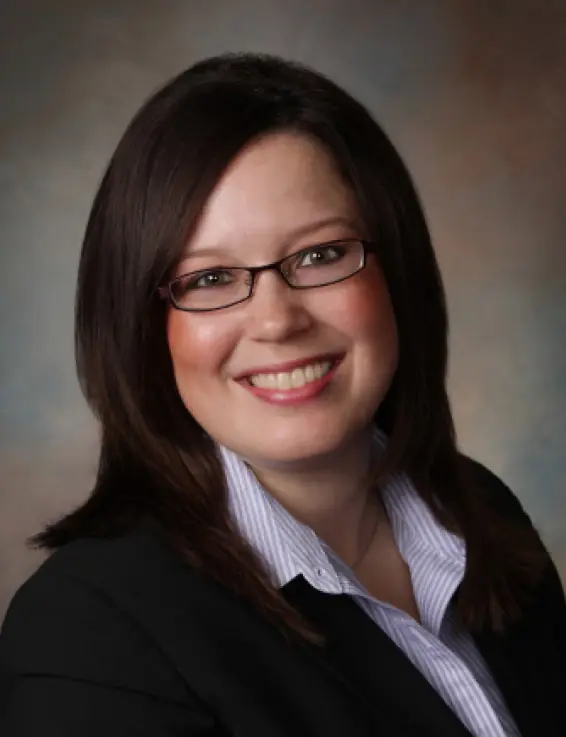
Portrait of attorney Rosalind M. Robertson

Rosalind M. Robertson

Elder law attorney

Rosalind spent time with both of her grandmothers in nursing homes, one with Alzheimer’s and the other after a fall, and she saw the emotional and financial toll it took on her family. She personally takes the firm’s first crisis calls. She helps families understand what may be protected and what the next step should be. Licensed in Missouri and Illinois.

Questions after admission

Clear answers before your family commits to a course of action.

No. Many lawful Medicaid planning steps can still be taken after admission. What is possible depends on whether the person is married or single, the assets involved, past transfers, timing, and the person’s legal capacity.

That does not mean we cannot help. Many traditional powers of attorney leave out the powers an asset protection plan needs. If your parent can still understand and sign legal documents, we can often put an enhanced power of attorney in place, even in a crisis. A diagnosis such as dementia or Alzheimer’s does not by itself mean a person cannot sign. If your parent cannot sign, other options exist, so call before you assume it is too late.

Not before the full situation has been reviewed. Paying real expenses can be fine, but unplanned spending can use up assets that might have been protected for a spouse or the family.

Not without a plan. Filing early can start coverage sooner, but the plan and the application need to work together. Filing first can limit what can be protected, and missing a state deadline can cost coverage. We coordinate both.

Often, yes. The standard calculation is where the analysis starts. Missouri planning may allow extra savings to be turned into protected income for the spouse at home, when the facts fit.

Potentially. Planning for one person is different. It often means protecting a portion of the assets while creating a carefully timed path to eligibility. Transfers made without a complete plan can make things worse.

Yes. When you hire us for a crisis plan, we design the strategy, tell your family exactly what to do, prepare and file the application, answer the state’s requests, and advocate for you until a decision is made.

Start before another month is paid

Find out what can still be protected before the next bill is paid.

You do not need to understand Medicaid or know which planning option applies. Give us the basic facts and Rosalind M. Robertson, an elder law attorney, will review your information and contact you.

Our goal is to respond within one business day. If a payment or application deadline is approaching, call 636.493.3333.

A short description is enough. Do not include account numbers or other sensitive financial information.

Please do not include Social Security numbers, account numbers, or other sensitive financial information.

Thank you. Your request was received. One moment while we take you to the next step.
Something went wrong. Please call 636.493.3333 and we will help you right away.
Call an elder law attorney